
Blogs
Finding the right person to care for your child is an important decision for every family. Parents want someone who is responsible, patient, experienced, and able to understand a child’s daily needs. A professional Nanny In Jaipur can provide dependable support with childcare, daily routines, meals, playtime, school preparation, and other age-appropriate activities while parents manage work and family responsibilities. In a growing city like Jaipur, families in areas such as Vaishali Nagar, Mansarovar, Malviya Nagar, Jagatpura, C-Scheme, Raja Park, Bapu Nagar, Pratap Nagar, Sanganer, and Durgapura increasingly look for reliable domestic support that can fit their household routine. Local service directories also show nanny, babysitting, and elder-care options across several Jaipur neighbourhoods, highlighting the importance of choosing a service that understands local family requirements.
Good Maid India provides domestic staffing solutions for families looking for dependable household and caregiving support. The company states that its staff are background checked and that it provides support and replacement assistance, with Jaipur among its service locations. For families, these checks and clear communication can make the process of hiring a nanny more comfortable and organized.
Why Choose a Professional Nanny In Jaipur?
A nanny does much more than simply stay with a child when parents are busy. A good nanny becomes part of the child’s daily routine and provides attentive support according to the family’s instructions. Depending on the arrangement, responsibilities can include preparing simple meals for children, helping with bathing and dressing, supervising playtime, assisting with school preparation, maintaining the child’s room and belongings, and ensuring that the child follows a healthy daily routine. Parents should always clearly discuss responsibilities, working hours, childcare expectations, and household rules before hiring.
Professional Nanny In Jaipur services can be particularly helpful for working parents, families with young children, parents who need support during extended working hours, and households where both parents have demanding schedules. The right nanny should be selected according to the child’s age, personality, routine, and specific requirements rather than simply choosing someone based on availability.
Childcare Support Designed Around Your Family
Every family has a different routine. Some parents may need a part-time nanny during office hours, while others may require full-time or live-in assistance. Families with infants may need someone who is comfortable with feeding schedules, diaper changes, nap routines, and constant supervision. Families with older children may require help with school preparation, homework supervision, outdoor play, and daily activities.
A reliable nanny should follow the parents’ instructions and maintain consistency in the child’s routine. Good communication between parents and the nanny is essential because it helps everyone understand responsibilities and creates a comfortable environment for the child.
What Services Can You Expect From A Nanny?
The exact responsibilities depend on the family’s requirements and the agreed service arrangement. A nanny may assist with everyday childcare activities while keeping the child safe, comfortable, and engaged.
Infant And Toddler Care
Infants and toddlers require close attention throughout the day. A nanny can assist with feeding according to the parents’ instructions, changing clothes and diapers, maintaining hygiene, preparing the child for sleep, and supervising play. Since young children can require attention at almost any time, parents should select someone who is patient and comfortable with the demands of infant care.
School-Going Child Care
For school-going children, nanny support can include helping them get ready in the morning, preparing their school essentials, serving meals, supervising homework, and maintaining a regular after-school routine. The nanny can also provide supervision during playtime and help children follow household safety rules.
Daily Routine And Activity Support
Children benefit from a balanced routine that includes meals, rest, learning, physical activity, and play. A responsible nanny can help maintain this routine while following the parents’ preferences. Simple activities such as reading, drawing, indoor games, supervised outdoor play, and age-appropriate learning can keep children active and engaged.
How Good Maid India Helps Families Find Nanny In Jaipur
Choosing domestic staff for your home requires trust. Good Maid India focuses on connecting families with domestic help and caregiving professionals across different Indian cities, including Jaipur. Its website highlights background checks, police verification, support, and replacement assistance as part of its service approach. These are useful factors for families to consider when comparing domestic staffing agencies.
Verification And Family Safety
When hiring someone to work inside your home and care for your child, verification should be treated seriously. Families should ask for identification, previous experience, references where available, and relevant background information. Good Maid India promotes verified and background-checked domestic staff, helping families make a more informed hiring decision. Parents should still communicate their expectations clearly and remain involved in their child’s care.
Flexible Nanny Requirements
Different families require different schedules. Some may need a nanny for a few hours every day, while others may require full-time assistance. Before hiring, discuss working hours, weekly holidays, duties, salary, food arrangements if applicable, and any additional responsibilities. Clear terms from the beginning can prevent misunderstandings later.
Nanny In Jaipur For Different Family Needs
Families living in Jaipur have different childcare requirements depending on their lifestyle and household structure. Working couples may need childcare during office hours, while families with newborns may need additional support throughout the day. Parents who travel frequently may also require dependable childcare assistance at home.
In areas such as Mansarovar, Vaishali Nagar, Malviya Nagar, Jagatpura, C-Scheme, Raja Park, Shastri Nagar, Bapu Nagar, Durgapura, Pratap Nagar, and Sanganer, families can look for childcare support based on their particular location and schedule. Local Jaipur care listings also show demand for home-based childcare and elderly-care assistance in neighbourhoods across the city.
Elder Care In Jaipur – Support For Senior Family Members
Many families need more than childcare assistance. They may also have elderly parents or senior family members who require help with everyday activities. Elder Care In Jaipur can include companionship, assistance with daily routines, mobility support, meal assistance, personal-care support, and reminders for routine activities according to family instructions.
Elder care should always be approached with patience and respect because senior citizens may need emotional support as much as practical assistance. Jaipur has elder-care services operating across areas such as Mansarovar, Malviya Nagar, Vaishali Nagar, Jagatpura, Bapu Nagar, Raja Park, C-Scheme, and other parts of the city. Families should select caregivers according to the senior’s individual needs and seek qualified medical professionals whenever medical or clinical care is required.
Respect, Companionship And Daily Assistance
A senior caregiver may help with walking support, meals, household coordination, companionship, and other daily activities. For elderly people living alone, having a dependable person around can also provide reassurance to family members who live in another city or have demanding work schedules. However, caregivers should not be treated as a substitute for doctors, nurses, or other licensed healthcare professionals when specialized medical care is needed.
Care Taker Services In Chandigarh For Families
Families outside Jaipur may also need dependable domestic and caregiving support. Care Taker Services In Chandigarh can be useful for senior citizens, patients recovering at home, individuals requiring daily assistance, or families that need an additional person to support household routines. Caretaking responsibilities should be agreed upon in advance and matched to the person’s experience and capabilities.
Chandigarh and the surrounding Tricity area have domestic-help providers offering services such as nanny care, elderly companionship, housekeeping, and trained drivers, showing how families increasingly look for specialized home support instead of relying only on informal arrangements. When selecting a caretaker, families should consider experience, reliability, communication skills, verification, working hours, and the specific needs of the person receiving care.
Driver Agnecy In Pune – Reliable Household Driver Support
Domestic support is not limited to childcare and elder care. Families may also require transportation assistance for school runs, office travel, shopping, hospital visits, or everyday family activities. A professional Driver Agnecy In Pune can help families identify drivers according to their schedule and driving requirements.
When selecting a household driver, families should check driving experience, licence validity, references, communication, punctuality, and familiarity with local routes. Safety should always be the first priority, particularly when the driver will be transporting children, elderly family members, or other dependants. Clear working terms and responsibilities should also be discussed before the driver starts working.
How To Choose The Right Nanny For Your Home
Selecting a nanny should involve more than a simple interview. Parents should understand the candidate’s previous childcare experience, communication style, availability, and ability to handle the responsibilities expected in the household. It is useful to explain the child’s daily routine and observe how the candidate responds to questions about safety, discipline, meals, play, and emergencies.
Families should also verify identity and references, clearly define job duties, agree on working hours, and maintain open communication after the nanny joins. A short orientation period can help the nanny understand the child’s routine and the family’s expectations.
Questions Parents Should Ask Before Hiring
Parents can discuss the candidate’s previous childcare experience, the age groups they have worked with, preferred working hours, experience with infants or school-going children, and willingness to follow the family’s childcare routine. Families should also ask how the nanny would respond to common situations such as a child becoming upset, refusing food, or needing immediate parental attention.
Why Trust Matters In Home Care Services
Home care is built around trust because caregivers work in a private family environment. A professional agency can make the hiring process more structured by helping families understand the available service options and verification procedures. Good Maid India promotes verified domestic staff, police verification, background checks, 24/7 support, and replacement assistance on its website. Families should still conduct their own discussions and verification checks and establish clear expectations before confirming a placement.
Choose Good Maid India For Reliable Home Support
Finding dependable childcare or caregiving support should not feel like a rushed decision. Whether your family needs a Nanny In Jaipur , Elder Care In Jaipur , or domestic support in another city, the right professional should be selected according to your family’s actual requirements, schedule, and safety expectations.
Good Maid India provides domestic help services across Jaipur and many other Indian cities and presents itself as a platform connecting families with verified domestic staff. For families looking for dependable household assistance, a structured hiring process, clear communication, and proper verification can make a significant difference.
If you are looking for a reliable Nanny In Jaipur , discuss your childcare requirements with Good Maid India and choose a service arrangement that fits your family’s routine. With the right support, parents can manage their professional responsibilities with greater peace of mind while children receive consistent attention, care, and companionship at home.
PW Consulting Report: Worldwide Prostaglandins Market to Expand from USD 16,166 Million in 2025 to USD 23,129 Million by 2032 at 5.24% CAGR — Ophthalmology, PGF2α and North America Lead
By pmarketresearch, 2026-08-18
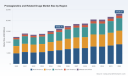
Worldwide Prostaglandins and Related Drugs Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on Worldwide Prostaglandins and Related Drugs synthesizes seven years of market performance and a seven‑year forward view to equip life‑science executives with the situational clarity they need for 2026. The prostaglandins market has demonstrated resilient growth through recent volatility; our base‑year assessment pegs global revenue at approximately USD 16.17 billion in 2025, and our model projects expansion to roughly USD 23.13 billion by 2032 — a compound annual growth rate (CAGR) of 5.24% across the forecast window. This press summary distills the report’s strategic takeaways while reserving the granular subsegment and regional tables for the full deliverable.
Ambient Light Indoor Solar Cells Market
Executive snapshot: Why prostaglandins matter in 2026
-
Enduring therapeutic relevance: Prostaglandin analogs remain foundational across ophthalmology, cardiovascular care and select niche indications — a mix of mature, high‑volume ophthalmic assets and targeted specialty uses that continues to attract innovation and competitive entry.
Worldwide Cloud Core Financial Management Suites Market -
Dual‑track market dynamics: Growth is being driven by expanding clinical indications and population ageing in developed markets, while pricing pressure and generic penetration are reshaping commercial strategies and margins.
Worldwide Construction Temporary LED Lighting Market -
Supply chain and manufacturing premium: Proven API capabilities and secure, backward‑integrated production are now material strategic advantages — evidenced by recent capacity investments and the entry of large generics into previously branded territories.
Macro trajectory and what it signals for 2026 decisions
Our calibrated market model integrates historical sales (2020–2025) and forward demand drivers to produce a high‑resolution outlook. With 2025 revenue near USD 16.2B and a 5.24% CAGR to 2032, the market is large enough to sustain multiple commercial strategies: premium branded life‑cycle extensions, differentiated delivery systems, and a robust generic market. However, the headline growth conceals two strategic tensions that leaders must navigate in 2026: (1) the need to secure reliable API and finished‑dose supply in a period of reshoring and capacity expansion; and (2) intensifying price competition in core ophthalmic classes as additional generic approvals and supply diversification accelerate.
Competitive landscape — players to watch
The prostaglandins ecosystem is a hybrid of integrated Western manufacturers, specialty API producers and multinational generic houses. Our concentration analysis shows a market that is meaningfully consolidated at the top but still offers room for mid‑market agility (CR3 ~42.5%; CR5 ~58.8%). Key strategic profiles in the report include:
-
EUROAPI — A Western API leader with a complete prostaglandin portfolio and unique backward‑integrated European production. Its capacity positioning and vertical integration make it a strategic partner for manufacturers seeking supply security and traceability.
-
Global brand leaders (Pfizer, AbbVie/Allergan, Novartis/Alcon) — These companies anchor the ophthalmic prostaglandin franchises and retain clinical mindshare through product familiarity and branded lifecycle tactics, including alternative delivery formats and patient support programs.
-
Large generics (Teva, Sun Pharma, Amneal) — Generics are compressing branded prices and expanding access. Recent regulatory approvals have reinforced the pace of commoditization in core ophthalmic molecules, creating both payer pressure and opportunity for differentiated sustained‑release or device‑integrated approaches.
-
Specialist API and mid‑market manufacturers (Chirogate, Everlight, Cayman, Newchem, C2 Pharma) — These suppliers supply intermediates and finished API to a wide set of drug product manufacturers. Their investments and capacity decisions act as early indicators of supply tightness or surplus.
Recent regulatory and commercial events — for example, new generic approvals and recent FDA clearances for ophthalmic entrants — have immediate implications for formulary dynamics and pricing negotiations in 2026. The full report contains company‑level scorecards, patent‑clock mapping, and scenario analyses for market share shifts following predictable generic cascades.
Regulatory inflection points and reimbursement trends
-
Regulatory approvals are re‑defining clinical use cases. The recent extension of indications for select prostanoids and emerging approvals in new acute settings have expanded potential addressable use, even as payers scrutinize incremental value.
-
Payer behaviour remains critical. Historical data show meaningful Medicare spend concentration on branded prostaglandin products, a pattern that amplifies the impact of patent expiry and generic substitution on national budgets and contracting leverage.
-
Device and sustained‑release formats change the commercial conversation. Implantable and sustained‑release prostaglandin products introduce new pricing anchors and health‑economic narratives that branded manufacturers can leverage to protect value.
Supply chain, manufacturing resilience and raw material risks
Supply security has moved from operational concern to strategic imperative. The market is witnessing targeted investments in capacity and regional reshoring by API specialists — developments that materially affect sourcing decisions for drug‑product manufacturers and contract development and manufacturing organizations (CDMOs). Raw‑material volatility, regulatory scrutiny of cross‑border supply chains, and the premium on backward‑integrated producers mean that manufacturers without secured off‑takers or multi‑sourced supply lines face elevated risk in 2026.
Strategic playbook for executive teams in 2026
PW Consulting’s report translates market projections and competitive intelligence into an actionable playbook. Key strategic levers for 2026 include:
-
Portfolio prioritization: Segment your pipeline and in‑market SKUs into defend, differentiate and divest buckets using relative margin potential, patent timelines, and payer sensitivity.
-
Manufacturing and sourcing strategy: Secure multi‑tiered supply contracts with backward‑integrated API providers or invest in joint capacity to mitigate single‑source exposure.
-
Commercial differentiation: Pursue delivery innovations and bundled care pathways (e.g., implantable devices, combination therapies) to create payer‑attractive value beyond molecule price.
-
M&A and partnership archetypes: Target bolt‑on API assets, niche device players, or specialty manufacturers that provide either supply security or route‑to‑market leverage in ophthalmology and specialty indications.
-
Regulatory and HTA readiness: Build dossiers for outcome‑based contracting and prepare health‑economic models ahead of reimbursement discussions to defend premium pricing for differentiated products.
What the PW Consulting report delivers (practical outputs)
For teams preparing 2026 budgets and strategic plans, the full report provides:
-
Proprietary market model with scenario toggles for generic entry timing, reimbursement shocks and new‑indication uptake — exportable to Excel for internal stress‑testing.
-
Risk matrix and supplier scorecards mapping production footprint, regulatory track record and capacity lead times for the full supplier universe.
-
Company and asset dossiers that synthesize patent positions, clinical evidence strengths, recent regulatory actions, and commercial positioning (including recent generic approvals and branded life‑cycle moves).
-
Investment and deal playbooks with target screening criteria and valuation reference ranges for strategic acquisitions, minority stakes and joint ventures.
-
Operational checklists for supply continuity, contract renegotiation templates, and go‑to‑market tactics for differentiated ophthalmic and specialty prostaglandin products.
Implications for specific board‑level choices
Boardrooms must reconcile short‑term margin pressures against the long‑term value of scale and differentiation. In 2026, actionable choices include accelerating capacity partnerships with backward‑integrated API suppliers, prioritizing investment in delivery innovations that preserve price realization, and deploying targeted M&A to secure niche manufacturing or device capabilities. Our thesis is simple: companies that align clinical differentiation with supply assurance and proactive payer evidence will capture disproportionate share and margin as the market evolves.
Why PW Consulting’s approach matters
We combine primary interviews across manufacturers, CDMOs, and payers with transactional and regulatory intelligence to make the forecast operational. The report is purposely structured to move beyond high‑level projections and into executable decision frameworks. That includes detailed sensitivity analyses, supplier contingency plans, and quantified commercial scenarios tailored for board and operational teams preparing FY‑2026 plans.
Next steps and access to the full intelligence
This press summary is designed to demonstrate the strategic depth of the full study while withholding detailed subsegment tables and regional breakdowns to protect our clients’ competitive advantage. For procurement teams, business development leaders, corporate strategy groups and investors preparing for 2026, the full report contains the granular data, downloadable models and supplier‑level intelligence required to convert insight into implementation.
To obtain the complete Worldwide Prostaglandins and Related Drugs Market report, the accompanying Excel model, and advisory briefings tailored to your organisation’s role in the value chain, please contact PW Consulting. Our analysts are available to walk through scenario runs, supplier risk simulations, and bespoke M&A target screening ahead of your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Prostaglandins and Related Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report: Worldwide Scar Treatment Supplies Market forecast to grow at a 10% CAGR during 2026–2032
By pmarketresearch, 2026-08-18
Worldwide Scar Treatment Supplies Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on Worldwide Scar Treatment Supplies provides an executive-grade strategic lens for companies planning investments, product launches, or partnership moves in 2026. Our research shows the market reached approximately USD 25,120.45 Million in 2025 and is projected to expand at a compounded annual growth rate (CAGR) of 10.0% through the forecast window. Under that trajectory, the market is modeled to approach roughly USD 48,952.67 Million by 2032—a scale and growth profile that materially changes competitive calculus for manufacturers, distributors, and healthcare providers.
Tray Former Machines Market
Why this report matters for 2026
- Decision-focused intelligence: The study synthesizes macro growth, regulation, and supplier dynamics into actionable decision triggers—when to invest in capacity, when to pursue M&A, and which product development bets have the highest risk-adjusted returns.
- Tactical timing: 2026 will be pivotal for firms that want first-mover advantage on upgraded regulatory pathways and differentiated product claims. Our timing scenarios map investment windows against regulatory milestones.
- Competitive clarity: With an intermediate degree of market concentration (CR3 and CR5 metrics showing meaningful but not prohibitive aggregation), there is room both for scale plays and targeted niche strategies. The report decodes where scale matters and where focused clinical evidence can beat brand recognition.
- Risk-managed opportunity: We translate macro growth into portfolio-level priorities—showing where to accelerate R&D, where to preserve margin via pricing, and how to structure partnerships to hedge regulatory and reimbursement risk.
What the report delivers — operationally usable content
We designed this study to be a working tool for commercial, strategy, and R&D teams. Key deliverables include:
Worldwide Enterprise Payment Software Market
- Market sizing and a transparent methodology (historical 2020–2025 base plus forward modeling to 2032) calibrated to both top-down and granular bottom-up inputs.
- Opportunity matrices that prioritize product categories and clinical use-cases based on accessibility, reimbursement tailwinds, and unit economics.
- Go-to-market playbooks for OEMs, private-label manufacturers, and hospital procurement teams—covering route-to-market, pricing architecture, and channel mix optimization.
- Regulatory impact scenarios mapping FDA and EU MDR pathways to time-to-market and cost-to-compliance for leading product classes.
- Supplier and manufacturing assessment including cost drivers, capacity signals, and recommended near-term capex strategies.
- Commercial risk matrices and sensitivity analyses—stress-testing revenue forecasts against adverse regulatory rulings, ingredient shortages, and price-competitive entry.
- Detailed competitor dossiers and a deal tracker highlighting recent certifications, product launches, and strategic moves across the landscape.
Market dynamics shaping 2026 strategy
Three structural forces are governing the scar treatment supplies market heading into 2026:
Pharmacogene Testing Market
- Clinical and consumer convergence: Medical-grade silicone and hydrogel technologies remain core, but consumer-focused topical products and OTC propositions are pushing clinical suppliers to refine claims and packaging. This convergence creates both premiumization opportunities and margin compression risks.
- Regulatory tightening in major markets: In the U.S., many silicone-based products remain regulated under established FDA device codes and general controls, which preserves quicker market access for some legacy products. In contrast, the EU trend toward higher-class MDR certifications has increased conformity costs, as demonstrated by recent Class IIb clearances for scar-related devices—an inflection that will influence where companies choose to prioritize certification investments.
- Consolidation vs. differentiation: Concentration metrics indicate a market where the top players command significant share but do not create insurmountable barriers to entry. That creates a dual strategic path: scale-driven margin plays for incumbents and evidence-driven, niche clinical strategies for challengers.
Competitive landscape — what to watch in 2026
The market is populated by a mix of large medical-device incumbents, specialized silicone innovators, and diversified OTC players. Our competitive review focuses on strategic posture rather than incremental product specs, highlighting where each type of player is likely to succeed:
- Established medical-device companies (examples include multinational firms with surgical and wound-care portfolios) benefit from global distribution, clinician relationships, and contract manufacturing scale. For these players, the playbook is to fortify clinical evidence for prophylactic use and integrate scar management into perioperative care pathways.
- Silicone specialists offer deep IP and product differentiation in formulations and adhesion systems. These firms can win by accelerating claims substantiation, securing regulatory certifications in high-value markets, and expanding into adjacent wound-care segments.
- Consumer-health and OTC brands focus on shelf visibility, e-commerce, and brand trust. They have shorter product cycles but face margin pressure; strategic partnerships with clinicians or value-added packaging can lift perceived clinical legitimacy.
- Technology innovators exploring alternative actives (e.g., hypochlorous acid-based gels) and hybrid delivery systems present high upside but require careful regulatory and clinical pathways.
Notable strategic developments underscore these dynamics. A leading hypochlorous-acid supplier completed EU MDR Class IIb certification for key scar and wound-care products—an example that demonstrates the growing imperative to invest in sustained regulatory compliance to access higher-margin institutional channels. Across the board, companies are pursuing differentiated adhesion technologies, evidence from randomized trials, and targeted distribution alliances.
Strategic playbook for 2026 — recommended actions
We recommend the following priority actions for companies that want to convert the market’s growth into durable competitive advantage.
- Targeted clinical investment: Prioritize randomized or real-world studies that substantiate prophylactic use and long-term cosmesis outcomes. Clinical evidence increases formulary acceptance and justifies premium pricing.
- Regulatory hygiene and scenario planning: Prepare for elevated conformity expectations in key export markets. Build regulatory timelines into your commercial launch plan and model price and margin impacts of certification-driven cost increases.
- Portfolio rationalization: Use a fact-based opportunity matrix to decide where to scale versus where to divest. Some product classes are margin-rich but require scale; others offer high clinical differentiation with lower production complexity.
- Channel diversification: Strengthen e-commerce, telehealth-enabled distribution, and hospital supply agreements in parallel. A two-track channel approach mitigates the risk of retailer-driven price pressure while capturing clinical demand.
- Partnerships and M&A calibration: For incumbents, bolt-on acquisitions or strategic alliances can accelerate entry into specialty actives or novel adhesion systems. For challengers, licensing or distribution partnerships with larger players are often the most capital-efficient paths.
- Manufacturing and supply resilience: Prioritize supplier redundancy for critical silicone polymers and adhesives. Lean manufacturing investments that lower per-unit costs will be decisive as the competitive field intensifies.
Risks and scenario planning
Key downside risks to model in 2026 planning include rapid regulatory reclassification in large markets, raw-material shortages or price shocks in silicone feedstocks, and a pricing squeeze from large private-label buyers. Upside scenarios include accelerated prophylactic adoption in elective surgery programs and validated claims for novel actives that expand addressable patient populations.
How PW Consulting’s report helps you operationalize the insight
Our study is built to be used, not simply read. Alongside the narrative and strategic recommendations, the report supplies executable templates—commercial launch checklists, regulatory certification timelines, and M&A valuation heuristics—so leadership teams can convert insights into roadmaps in weeks, not months. We intentionally withhold proprietary micro-segmentation in this public preview to preserve the report’s tactical value; however, the full report contains the granular regional and product-level breakouts, modeled pricing curves, and downloadable Excel modules used by our consultants when advising clients.
Next steps
- For an executive briefing and a demo of the report’s modeling workbook, contact PW Consulting to schedule a strategic workshop tailored to your portfolio and geographic priorities.
- Organizations focused on near-term launches should request our regulatory impact supplement, which maps certification paths and expected timelines by jurisdiction.
- Companies considering M&A or partnership activity can commission a bespoke target-screening exercise drawn from the report’s competitive dossier and deal tracker.
PW Consulting’s Worldwide Scar Treatment Supplies Market report gives commercial leaders the evidence-based framework they need to make confident, time-sensitive decisions in 2026. To access the full data, proprietary segmentation, and actionable annexes that underpin these findings, please visit PW Consulting’s report page or contact our client services team for an immediate briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Scar Treatment Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RIM Systems Market Valued at USD 1.95 Billion in 2025, Forecast to Reach USD 3.40 Billion by 2032 at an 8.25% CAGR
By pmarketresearch, 2026-08-18
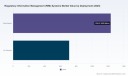
PW Consulting Strategic Brief: Regulatory Information Management (RIM) Systems Market Outlook — Why 2026 Is the Inflection Point for Enterprise Decision-Making
Executive summary
As regulatory complexity and digital transformation accelerate across life sciences and medical device industries, Regulatory Information Management (RIM) systems are moving from a niche compliance utility to a strategic backbone for commercialization, risk mitigation, and data-driven regulatory intelligence. Our new market study, anchored on 2025 as the base year, shows the global RIM systems market reached USD 1,950 Million in 2025 and is on a sustained growth path — with an 8.25% compound annual growth rate forecast across the 2026–2032 horizon. By 2032 our forecasts indicate the market will exceed USD 3.3 billion.
UART Transceiver Market
This briefing highlights the actionable implications of those macro dynamics for enterprise strategy in 2026: vendor selection, sourcing models, operating model changes, and the data governance and privacy safeguards that now determine whether RIM investments deliver measurable business value.
Discharge Printing Market
Why 2026 matters: regulatory inflection meets technology maturation
-
Regulatory complexity is increasing. Global agencies are modernizing submission formats and imposing stricter rules on electronic records and signatures (notably 21 CFR Part 11 requirements in FDA-regulated contexts). At the same time, data privacy regimes such as GDPR and CCPA — and a growing slate of state-level privacy laws — constrain the technical and contractual approaches companies can take to manage regulatory data. Enterprises choosing or upgrading RIM in 2026 must plan for both compliance and agility.
Figure Skates Market -
Technology shifts are reshaping vendor value propositions. Cloud-native architectures, AI-enabled authoring and monitoring, and integrated submission engines are moving from product differentiators to expected capabilities. The market’s growth profile reflects this transition: buyers increasingly prize platforms that combine regulatory domain models with automation and analytics rather than standalone document repositories.
-
Commercial imperatives create urgency. Faster time-to-market, the need for harmonized global registrations, and the operational cost of manual regulatory workstreams are pushing organizations to treat RIM as an enterprise system rather than a departmental tool. 2026 is the moment to decide whether to modernize incrementally or transform regulatory operations end-to-end.
Market structure and competitive dynamics — what strategists need to know
The RIM market sits in a moderate concentration band: the top three vendors account for roughly 45% of market share and the top five for about 58%. This structure produces a dual-track competitive landscape. On one track, larger, full-suite vendors emphasize global scale, integration with broader life sciences platforms, and enterprise-grade support. On the other, specialized and regionally focused providers compete on rapid implementation, MedTech-specific workflows, or prescriptive regulatory intelligence.
Key competitive themes enterprises should evaluate in 2026:
-
Depth versus breadth: Does the vendor offer deep, use-case specific capabilities for your therapeutic or device category, or broader coverage across submissions, registrations, and post-market commitments?
-
Cloud-native and multi-tenant maturity versus hybrid/on-prem options — and the migration pathways between them.
-
Embedded intelligence — AI for submission authoring, regulatory monitoring, and automated impact analysis — and how that intelligence is trained, validated, and governed.
-
Services model: software-only versus offerings with regulatory consulting, data migration, and managed services that de-risk deployments.
Vendor landscape: strategic profiles and selection considerations
Below are synthesized strategic profiles of the vendors that consistently appear in enterprise vendor shortlists. These snapshots emphasize positioning and buyer considerations rather than raw feature checklists.
-
Rimsys (Pittsburgh, PA) — A platform purpose-built for MedTech with an emphasis on global registrations, submissions, product master data and change management in a unified system. Recent product innovation (Spring 2026 Regulatory Execution Engine) embeds submission authoring, AI-powered regulatory monitoring, and configurable impact workflows — signaling a move toward combining execution and intelligence in a single offering. Consider Rimsys for MedTech-focused programs seeking rapid, domain-specific implementation.
-
Veeva Systems (Pleasanton, CA) — Veeva Vault RIM is a widely adopted cloud-based solution that integrates submissions, registrations, publishing and archival capabilities. Veeva’s strength is enterprise-scale integration with commercial and clinical suites; organizations with existing Veeva footprints will find architectural and operational synergies.
-
IQVIA (Durham, NC) — With SmartSolve RIM, IQVIA couples cloud delivery and AI-enabled submission tooling with deep services capability. It is a compelling choice for sponsors seeking combined software and regulated process outsourcing.
-
Kivo (Portland, OR) — Focused on life sciences regulatory needs, Kivo emphasizes document and process management with compliance workflows for major authorities. Its value proposition centers on simplicity and fast time-to-value for sponsors and CROs.
-
Ennov (Paris, France) — Ennov’s RIM product centralizes product, registration, submission, correspondence and commitment data, and is often selected by organizations needing strong European regulatory coverage and configurable data models.
-
MasterControl (Salt Lake City, UT) — MasterControl’s RIMS Rx has a track record in regulated manufacturing contexts and appeals to organizations where regulatory information converges tightly with quality and release processes.
-
ArisGlobal (Waltham, MA) — LifeSphere RIMS offers end-to-end regulatory planning, tracking and registration management, increasingly augmented with AI capabilities. ArisGlobal targets enterprises seeking an integrated lifecycle platform with analytics.
-
RegDesk (Houston, TX) — A RIM platform positioned for MedTech with centralized regulatory data, global compliance workflows and regulatory intelligence. It is often shortlisted for companies prioritizing regulatory device-specific intelligence.
-
Freyr Solutions (Princeton, NJ) — Freyr bundles RIMS with broader regulatory outsourcing, offering lifecycle management and compliance services appealing to firms that prefer a managed-solution model.
What our report delivers — practical content for 2026 decision-makers
We designed the full study to be operationally useful for procurement, regulatory operations, IT and corporate compliance teams. Highlights include:
-
An executive scoring framework for vendor shortlists that weights regulatory coverage, technical architecture, data governance, and services models — designed to be customized for therapeutic area and organizational scale.
-
Procurement playbooks and contract clauses addressing intellectual property, data residency, audit rights, and incident response obligations tied to current privacy regimes.
-
Implementation templates: phased migration roadmaps, sample KPIs for pilots, and a risk register for common RIM program pitfalls.
-
TCO and ROI modeling templates that integrate licensing, implementation, data migration, and ongoing governance costs so buyers can move beyond vendor sticker prices.
-
Vendor dossiers and corroborated reference notes that synthesize product capabilities, service overlays, and deployment case studies. (Note: detailed regional and application segment tables are included in the full report to support prioritized vendor shortlists.)
Actionable recommendations for 2026 procurement and implementation
-
Define the business outcomes before selecting technology. Prioritize use cases (e.g., global registration orchestration, regulatory intelligence for post-market changes, submission automation) and quantify expected cycle time or cost reductions for each to build a defensible business case.
-
Adopt a phased modernization strategy. Start with a constrained pilot that validates data models, submission automation and security controls, then scale to additional regulatory domains and geographies. This approach reduces program risk and accelerates learning.
-
Require explicit data governance and privacy artifacts. Contracts should include data processing addenda aligned to GDPR/CCPA, support for electronic records compliance (e.g., 21 CFR Part 11), and a clear operational playbook for responding to state-level privacy requests.
-
Evaluate vendor AI capabilities under a governance rubric. Ask for transparency on model training data, change-control for models that generate regulatory text, and validation evidence demonstrating improved quality or speed without increasing compliance risk.
-
Design integration patterns with existing IT estates. Favor vendors with robust APIs, canonical data models and connectors to master data systems (product, quality, safety) to avoid creating new silos.
-
Plan for change management: map impacted stakeholders, define new RIM-driven roles (e.g., regulatory data stewards), and budget for cross-functional training aligned to the phased rollout.
Conclusion — the strategic choice facing 2026 leaders
The RIM systems market is no longer only about compliance. With sustained market growth and continued vendor innovation, RIM platforms are becoming strategic levers for regulatory speed, commercial readiness, and corporate risk control. The decisions organizations make in 2026 — about vendor archetype, deployment model, and integration approach — will determine whether their regulatory function scales or remains a bottleneck.
PW Consulting’s full Regulatory Information Management Systems Market report provides the segmented analysis, vendor-level scoring, implementation playbooks and datasets needed to move from strategy to execution. For an in-depth view of our methodologies, vendor dossiers, and the segmented intelligence that informed our market model, please consult the complete report on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Regulatory Information Management (RIM) Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Chassis-by-Wire Market to Grow at 19.5% CAGR, Reaching USD 29.3 Billion by 2032
By pmarketresearch, 2026-08-18
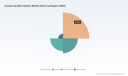
Worldwide Chassis-by-Wire System Market — Strategic Preview for 2026 Decision‑Makers
As the vehicle architecture shifts from mechanical architectures to software-defined systems, chassis-by-wire technologies (brake-by-wire, steer-by-wire, shift-by-wire and suspension-by-wire) have moved from niche proofs-of-concept to a foundational architecture for electrified, highly automated and connected vehicles. PW Consulting’s new Worldwide Chassis-by-Wire System Market study — based on a 2025 base year, a 2020–2025 historical window and a 2026–2032 forecast horizon — frames the commercial and technical inflection points that will define supplier strategies, OEM platform choices and investor decisions across 2026.
Worldwide Cloud Management Platform (CMP) Market
Macro picture: scale, speed and what it means for 2026
Our model shows the global chassis-by-wire market growing at a compound annual growth rate (CAGR) of 19.5% through 2026–2032. Measured in USD (revenue in millions), the market crosses the USD 10.1 billion threshold in 2026 under our base case and continues to compound materially toward the end of the forecast window. That pace of expansion alters traditional timeframes for ROI on new production lines, accelerates payback on software investments, and makes near‑term decisions (supplier selection, standards compliance, pilot deployments) strategically consequential for programs that begin production in 2027–2029.
3 Axis Horizontal CNC Milling Machine Market
Why this report matters for a 2026 strategy
- Decisions have shorter runway and higher stakes. The combination of high CAGR and rapid OEM platform commitments compresses evaluation and procurement cycles. Suppliers and OEMs that standardize architectures and establish validated safety cases in 2026 will capture preferential program positions for the next vehicle generation.
- Software and safety dominate capital allocation. The market is no longer just about actuators and sensors: software-defined motion control, validated fail‑operational architectures and cybersecurity stacks now represent a majority of program complexity and sunk cost. 2026 budget cycles must prioritize software lifecycle, over-the-air update strategies and functional safety investments at ASIL‑D level.
- Standards engagement is a competitive moat. With ISO 19725 entering publication activity and national rules (for example, recent Chinese steering system standards) updating the permissible architectures for steer-by-wire, active participation in standards and pre‑competitive groups materially reduces certification risk and time‑to‑market.
- Regional integration strategies matter. Standard harmonization (UNECE R79 allowances, China’s national standard updates, and ISO/SAE cybersecurity expectations) creates regionally differentiated compliance workstreams. A “global design, regional validation” approach is the pragmatic path for suppliers who aim for scale without proliferating SKUs.
What is in the PW Consulting report — practical, transaction‑ready content
PW Consulting designed this report to be operational for teams executing 2026 programs. Key deliverables include:
Worldwide Structural Engineered Glued Laminated Timber Market
- Market sizing and consensus forecast model (historical 2020–2025; forecast 2026–2032) with adjustable scenario levers (adoption timing, EV penetration, autonomy tranche) so procurement and strategy teams can run bespoke projections for their program timelines.
- Vendor benchmarking and capability scorecards across product, software, validation and production readiness — built from supplier interviews, public filings and in‑vehicle validation data.
- Standards & regulation readiness matrix mapping ISO 26262/ISO 19725 expectations, UNECE requirements and recent national standards to design and test deliverables needed for type approval and homologation.
- System‑level architectural playbooks (redundant controller options, dual‑power strategies, actuator redundancy patterns) with integration checklists to accelerate safety case generation.
- Supply chain risk register and unit cost/TCO modelling, including sensitivity to semiconductor availability and actuator sourcing, plus practical procurement mitigation measures.
- Go‑to‑market and M&A playbooks: target lists, valuation heuristics for strategic tuck‑ins (actuators, software stacks, functional safety houses), and JV models for China market entry.
- Operational templates — test protocols, cybersecurity hardening checklists, and sample ASIL‑D validation plans that can be adapted into supplier contracts and SRR/PRR milestones.
To preserve the commercial integrity of client deliverables and to comply with our “trailer” approach, the release intentionally omits granular region/application splits and line‑by‑line revenue tables from this public summary. The full dataset, vendor market shares and downloadable financial models are available in the PW Consulting report package and online portal.
Competitive landscape — who matters in 2026 and why
The supplier ecosystem is evolving into a landscape where systems integrators, traditional Tier‑1s and semiconductor specialists all play decisive roles. Our competitive analysis focuses on strategic positioning and near‑term moves that will influence awards in 2026:
- Continental AG — Positioned as an integrated systems supplier, Continental blends brake‑by‑wire and chassis control software with end‑to‑end vehicle integration capabilities aimed at software‑defined vehicle platforms. Expect continued emphasis on OEM partnerships and software monetization.
- ZF Friedrichshafen AG — ZF’s breadth (one‑box systems, hybrid portfolios for electrified platforms) gives it an advantage in multi‑domain program bids. The company’s 2025 portfolio unveilings show a strategy of offering modular stacks that reduce OEM integration effort.
- Robert Bosch GmbH — Bosch is strengthening full chassis integration with deep ADAS and automated driving alignment; their systems are attractive to OEMs that want a single supplier to assume broader validation responsibilities.
- Nexteer Automotive — The 2025 Electro‑Mechanical Brake product launch and subsequent ASIL‑D certification activity position Nexteer as a notable challenger in brake‑by‑wire and steer‑by‑wire for mass market EVs. Its active role in Chinese standards development is a strategic lever for access to local OEM programs.
- JTEKT Corporation — Focused on steer‑by‑wire scaling for EV and autonomous platforms; JTEKT is a contender where OEMs prioritize compact, high‑margin steering modules.
- Schaeffler AG — Building integrated actuation solutions with emphasis on density and packaging for electric platforms; attractive for OEMs looking to consolidate actuator sourcing.
- thyssenkrupp AG — Innovating on feedforward control and vehicle motion control integration, offering differentiated system behaviors for ride-and-handling tuning.
- Kongsberg Automotive — With fail‑operational systems and targeted acquisitions, Kongsberg is positioning for autonomous and commercial vehicle applications where robustness and certification are critical.
- Infineon Technologies AG — As a semiconductor enabler, Infineon’s high‑safety chipsets de‑risk motor control and safety islands — a strategic supplier for both established Tier‑1s and software-first entrants.
Market concentration metrics show a mid‑level consolidation dynamic — the top three suppliers capture a meaningful share of demand while the top five expand that reach further. That structure favors both incumbent scale and focused challengers that can exploit software or regional partnerships.
Regulatory and standards landscape — the guardrails for 2026 programs
- New standard activity (for example, the publishing process around ISO 19725) and national updates to steering system standards have shortened certification timelines: programs that align architectures to emerging guidance will avoid costly redesigns later in the development cycle.
- Functional safety and cybersecurity are non‑negotiable: ISO 26262 at ASIL‑D and ISO/SAE 21434 cybersecurity expectations drive architecture decisions (redundant controllers, dual power domains, fail‑operational strategies) and will be decisive in supplier selection rounds.
- UNECE R79 updates that allow steer‑by‑wire without mechanical backup under defined conditions open new packaging and space advantages for EV platforms — but they also increase the importance of validated self‑centering and fault management strategies.
Actionable 90‑day playbook for 2026
- Run a rapid architecture audit: map existing vehicle platforms to a standards readiness checklist and identify missing functional safety artefacts required for ASIL‑D certification.
- Initiate a supplier gate review: prioritize suppliers with validated redundancy architectures and semiconductor roadmaps, and require proof points on in‑vehicle failure mode testing.
- Lock a standards engagement plan: nominate technical leads to participate in ISO/industry working groups and track national standard timelines in priority markets.
- Budget for integrated software lifecycle: reallocate a portion of 2026 software spend towards OTA security, over‑the‑air validation and telemetry for in‑service fault analysis.
- Consider strategic investments or partnerships with actuator/semiconductor specialists to secure long‑lead components and preferential supply terms.
Closing perspective and next steps
Chassis‑by‑wire is transitioning from engineering novelty to strategic platform decision. The market’s high growth rate and regulatory momentum make 2026 a make‑or‑break year for supplier selection, standards engagement and architecture lock‑ins. PW Consulting’s Worldwide Chassis‑by‑Wire System Market study provides the forecasting backbone, vendor intelligence and implementation playbooks that procurement, engineering and corporate development teams will use to justify 2026 commitments.
We intentionally present this public summary as an executive “trailer” to our full deliverable: detailed regional and application splits, vendor market shares, financial models, and downloadable scenario workbooks are included in the complete PW Consulting report. For a walkthrough of the dataset, a tailored briefing for program timelines, or permissioned access to the model and vendor scorecards, contact PW Consulting to schedule a 2026 strategic briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Chassis-by-Wire System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Probe Cards Market to Grow from USD 2,940.0 Million in 2025 to USD 4,861.8 Million by 2032 at a 7.45% CAGR — Asia Pacific Leads with USD 1,978.6M, Top 3 Hold 58.4%
By pmarketresearch, 2026-08-18
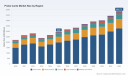
Worldwide Probe Cards Market — Strategic Preview for 2026: Why Senior Leaders Need This Compass
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a market preview that frames the probe cards industry for boardroom decisions in 2026. Our new report uses 2025 as the analytical base year and projects the industry through 2032. At the macro level, the probe cards market is forecast to expand at a compound annual growth rate (CAGR) of 7.45% across the 2026–2032 forecast window, rising from a market size of approximately USD 2,940 Million in 2025 to an expected USD 4,862 Million by 2032. These headline numbers encapsulate persistent secular demand from advanced logic, memory, and heterogeneous packaging test requirements — but they only begin to tell the story that matters for strategic action.
Worldwide Solid End Mills Market
Why this matters for 2026 decision-making
Probe cards sit at the intersection of semiconductor test performance, test cost, and time-to-market. For chipmakers, foundries, OSATs, and test equipment suppliers, small changes in probe card capability or lead time can cascade into significant yield, throughput, and economic outcomes. The PW Consulting report translates the financial trajectory above into operational levers organizations can use immediately:
Computer XTX and ETX Module Market
- Risk-adjusted sourcing strategies to mitigate lead‑time volatility driven by materials and geopolitics.
- R&D and product roadmap choices that prioritize probe card architectures most likely to deliver near-term performance advantages at advanced nodes and high-pin-count wafers.
- Partnership and M&A playbooks focused on acquiring scarce MEMS know-how, vertical spring optimization, and localized production capacity.
In short, the market’s growth is meaningful and sustained, but it is neither uniform nor frictionless. Executives must translate forecasted expansion into tactical commitments that de‑risk supply and sharpen competitive differentiation.
RF Probe Holder Market
Key market dynamics shaping 2026 strategies
-
Technology mix and node transitions: The push to advanced nodes and chiplet/3D packaging increases demand for high‑precision probe solutions (MEMS, vertical architectures and specialized fine‑pitch designs). As a strategic priority, product and test engineers should prioritize multi‑architecture roadmaps that maintain compatibility across legacy and next‑gen wafer formats.
-
Concentration and supplier economics: The industry shows moderate-to-high concentration at the top end: the leading three firms capture more than half of the market, and the top five account for a clear majority. That structure benefits established providers with scale and IP, but it also creates openings for focused challengers with differentiated niche capabilities.
-
Supply chain and materials pressure: Geopolitical tensions, material shortages (including tungsten, copper and substrate materials), and policy-driven export controls have materially affected lead times — with industry observations of delays up to ~20% in recent years. Ceramic substrates (notably for 300mm applications) dominate relevant substrate demand and represented roughly an 84% share of the material segment in 2024, underscoring a single‑material dependence that buyers must manage.
-
Localized capacity expansion: Manufacturers are strategically investing in localized production and capacity expansions to shorten supply chains and capture regional demand. These investments change regional competitive dynamics and will affect lead times, qualification cycles, and incumbent relationships in 2026 and beyond.
Competitive positioning — what the major players are doing
Understanding competitor intent is crucial for offensive and defensive strategy. Our research synthesizes company disclosures, primary interviews, and industry filings to map where incumbents are investing — and why it matters to partners and buyers.
-
FormFactor Inc. (Livermore, CA): Continues to lead on scale and breadth, with recent M&A activity that adds MEMS patents and vertical spring enhancements. This reinforces FormFactor’s capability set around logic, foundry and high‑bandwidth memory testing and reduces time‑to‑market for vertically-integrated customers who require rapid qualification cycles.
-
Technoprobe S.p.A. (Italy): Expanding production footprint in Europe with a major new facility aimed at servicing regional fabs. The move signals a play to reduce lead times for European customers and to capture incremental demand driven by local wafer fabs and IDM reshoring initiatives.
-
Micronics Japan Co., Ltd. (MJC) & Japan Electronic Materials (JEM): Japanese suppliers continue to emphasize precision and qualification wins at the most advanced nodes. Recent co‑developed qualifications for leading foundries position these players as preferred partners for fine‑pitch, advanced node requirements.
-
MPI Corporation (Taiwan): Evolving from niche supplier to a strategic partner for AI/HPC testing through partnerships and targeted capacity expansion. Their investments in Taiwan aim to capture demand from local OSATs and IDM customers focused on AI chip validation.
-
Regional and specialized players (Nidec SV Probe, Feinmetall, Wentworth, STAr, and others): These firms reinforce differentiated value points — high‑voltage/current capability, specialized cantilever/knife‑edge contacts, and vertical architectures for specific application niches. They are the likely acquisition targets for global players seeking to fill capability gaps quickly.
Recent developments that recalibrate 2026 strategy
- Strategic acquisitions that expand MEMS IP and spring optimization capabilities.
- Facility expansions and capacity investments aimed at regional resilience (notably Europe and Taiwan).
- High‑profile supplier qualifications with leading foundries for 2nm and other advanced nodes.
- Partnerships between probe card manufacturers and OSATs to co‑develop chiplet‑ready and 3D/2.5D test solutions.
Each of these moves has practical implications for sourcing timelines, qualification workflows, and the negotiation dynamics between chipmakers and probe card vendors.
How buyers and suppliers should act in 2026 — prioritized recommendations
Our advisory synthesis translates market dynamics into pragmatic actions. Below are prioritized steps for procurement, product, and corporate strategy teams.
-
Procurement — pursue dual‑track sourcing and strategic buffer inventory: With material concentration and geopolitics elevating lead time risk, buyers should adopt dual‑sourcing for critical probe architectures and maintain strategic buffer inventories for long‑lead components (substrates, precision contacts). Scenario-based procurement contracts (including capacity reservations tied to roll‑rate commitments) can protect production ramps.
-
Product & test engineering — accelerate cross‑architecture compatibility: Invest in test methodologies and probe card specifications that support both MEMS and vertical/cantilever modalities where economically feasible. Prioritize investments that reduce qualification cycle time with foundries and OSAT partners.
-
M&A & partnerships — target capability fills over scale alone: Given the market’s concentration, targeted acquisitions (materials, MEMS IP, fine‑pitch capability) and co‑development alliances can be faster and lower risk than greenfield expansions for companies seeking capability parity.
-
Operations — localize where latency matters: For time‑sensitive test cycles (e.g., wafer acceptance tests for high‑value wafers), localized assembly and qualification can be a strategic differentiator. Investment in regional assembly lines and qualification labs should be economically modeled against the revenue exposure of the end devices being tested.
-
Risk management — stress‑test supplier networks: Build financial and operational stress tests into supplier evaluations, modeling scenarios that include material shortages, export restrictions, and rapid demand swings driven by AI/HPC design wins.
What the PW Consulting report delivers — practical content for immediate use
Our report is designed as an executable intelligence product for 2026 strategic planning. Key deliverables include:
- Macroeconomic and technology trend narratives that link semiconductor roadmaps to probe card demand.
- Forecasted market trajectory (2026–2032) with scenario variants and sensitivity analyses tied to node transitions and packaging shifts.
- Competitive mapping and capability gap analysis, including IP posture, manufacturing footprint, and recent M&A/partnership activity.
- Supplier selection framework and negotiation playbook tailored to probe card OEMs and chipmakers.
- Supply chain resilience playbook with stress‑test templates, inventory models, and regional manufacturing decision matrices.
- Practical TCO models and qualification roadmaps for migrating to new probe architectures while protecting yield.
- Executive slide set and board brief template optimized for procurement, operations, and R&D leaders to present recommended actions and investment cases.
This package is intentionally operational — designed to move from insight to execution within 30–90 days of adoption.
What we held back and why — the preview principle
To preserve the strategic value of the full report, this article intentionally omits granular segment tables and exhaustive regional/applicational splits that are central to supplier selection, competitive tendering, and investment valuation. The complete dataset — including decomposed regional, type, and application breakdowns, supplier financial overlays, and the full suite of scenario matrices — is available in the full PW Consulting Worldwide Probe Cards Market report. That repository also contains downloadable models you can run with your own inputs.
Final assessment — where to focus in 2026
Probe cards will remain a critical enabler of semiconductor throughput and yield as the industry scales advanced node and packaging complexity. The market’s projected growth to roughly USD 4.86 Billion by 2032 at a 7.45% CAGR is robust enough to justify prioritized investments, but the path to capture value requires deliberate moves: secure supply lines, accelerate cross‑architecture qualifications, and consider targeted M&A or partnerships to obtain specialized MEMS/IP and local capacity. Market concentration benefits incumbents, yet clear niches exist for agile suppliers that can deliver superior qualification speed, localized support, or niche technical capabilities for chiplet and 3D/2.5D applications.
For executives preparing capital allocation, procurement strategy, or R&D planning in 2026, the PW Consulting report is a decision‑ready tool. It links market numbers to operating levers and gives you the playbook to translate forecasted growth into defensible competitive advantage.
Access the full report
To obtain the complete Worldwide Probe Cards Market report — including the full dataset, supplier scorecards, scenario models and executable playbooks referenced above — visit our report page or contact PW Consulting’s industry practice. The detailed segment tables and downloadable financial models are published exclusively with the full report to preserve competitive value for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Worldwide Probe Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Electric Drivetrain Components Market to Soar from USD 153.16 Billion in 2025 to USD 564.36 Billion by 2032 at a 20.48% CAGR — Asia Pacific Leads with USD 83.07B, Electric Motors and BEVs Dominate
By pmarketresearch, 2026-08-18
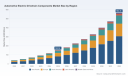
Worldwide Automotive Electric Drivetrain Components Market — Strategic Brief for 2026
PW Consulting’s new market study on the Worldwide Automotive Electric Drivetrain Components Market delivers the strategic intelligence senior leaders need as they set 2026 budgets, product roadmaps, and M&A agendas. The market that generated USD 153.16 Billion in 2025 has expanded rapidly from a 2020 base and — under current dynamics — is projected by our model to exceed USD 560 Billion by 2032, reflecting a compound annual growth rate of approximately 20.48% across the forecast window. Those headline metrics underscore a structural, capital-intensive shift in automotive powertrain economics: scale, platform modularity, raw-material exposure, and regulatory compliance will determine winners and losers over the coming 18–36 months.
Portable Blood Tube Sealer Market
Why this report matters for 2026 decision-makers
- Translate top-line growth into executable plans: Our analysis converts aggregate market momentum into tactical guidance for capex allocation, supply agreements, and product timing.
- De-risk technology choices: We map efficiency gains and cost trajectories across motors, inverters (including SiC adoption), and integrated e-axles so leadership can prioritize investments that preserve margin while meeting performance targets.
- Navigate supply-chain scarcity: The study overlays commodity concentration and semiconductor supply constraints onto supplier footprints to reveal where strategic stockpiles, alternative sourcing, or vertical integration are most urgent.
- Operationalize regulatory impact: With recent European legislative changes and particulate/ durability requirements maturing, the report identifies validation burdens and certification timelines that affect launch phasing and warranty exposure.
- Inform M&A and partnership strategies: Actionable heatmaps highlight acquisition targets, co-development matchups, and strategic investments that accelerate deployment of 400V/800V platforms and integrated drive systems.
Practical content you can use tomorrow
The report is built for boardrooms and strategy teams who must convert insight into action. It provides:
Disposable Balloon Uterine Lifter Market
- Robust methodology and traceable market-sizing — base year 2025 with full historical series (2020–2025) and a granular forecast for 2026–2032.
- Scenario-based outlooks that stress-test growth under alternative assumptions for commodity prices, regulatory tightness, and SiC supply bottlenecks.
- Technology deep dives on traction motors (including magnet vs magnet-free architectures), power electronics (Si vs SiC trajectories), integrated e-axles and multi-speed transmissions for electric platforms.
- Supplier profiles and capability matrices that rank OEM and Tier-1 positions on integration, vertical control, manufacturing scale, and software/controls ownership.
- Supply-chain risk maps and mitigation playbooks — from hedging rare-earth exposure through design choices, to procurement approaches for SiC and critical copper and lithium inputs.
- Commercial tools: price elasticity models, total cost of ownership worksheets for fleet customers, and negotiation frameworks for long-term component contracts.
- Interactive dashboards and downloadable data packages for internal modelling and committee briefings (note: detailed subsegment tables and proprietary supplier scores are included in the full package).
Key market dynamics shaping 2026 strategy
- Technology modularity and platform consolidation. Leading suppliers are investing in modular electric-drive architectures to shorten development cycles and serve multiple vehicle segments from a single platform. Modular solutions reduce per-unit cost at scale and increase cross-program reuse — a pivotal capability as OEMs compress time-to-market.
- Transition to high-voltage architectures and SiC adoption. The migration toward 400V/800V topologies and silicon carbide inverters is accelerating efficiency and charging performance, but it introduces new supplier dependencies and cost trade-offs that will influence product positioning and system margins.
- Supply concentration in raw materials and semiconductors. Critical inputs are unevenly distributed. Processing capacity for permanent-magnet rare-earth materials remains geographically concentrated, and SiC production is scaling but still faces cost and capacity challenges. Meanwhile, lithium price dynamics and base-metal volatility continue to reshape battery and drivetrain economics.
- Regulatory tightening and validation complexity. Recent regulatory packages in Europe (including accelerated CO2 targets and particulate/durability requirements) increase certification burdens for drivetrains and ancillary systems. Early adopters who integrate validation pathways into design cycles will realize time-to-market advantage and lower warranty risk.
- Consolidation and differentiated supplier strategies. Market concentration is measurable: a relatively small group of global suppliers collectively capture a notable share of industry revenue and influence platform choices. That concentration creates both negotiating leverage for large OEMs and expansion opportunities for integrated Tier-1s that can offer systems-level solutions.
Competitive landscape — what the leaders are doing
Our competitor analysis synthesizes capability, product roadmaps, and recent commercial moves for the industry’s most consequential players. Highlights include:
Intelligent Device Operation and Maintenance System Market
- European engineering houses are intensifying investment in integrated e-drive solutions and thermal management systems to capture platform-level value. These firms are placing strategic bets on modular architectures that span passenger and commercial vehicle segments.
- Japanese and Asian manufacturers continue to leverage deep motor and manufacturing know-how to drive efficiency and scale in traction motors and integrated e-axles, while selectively partnering with European suppliers on system integration and validation.
- North American players are differentiating through power-electronics expertise, high-voltage charging systems, and SiC-based solutions that target fast-charging and high-efficiency segments.
- Specialist newcomers and cross-border entrants are advancing compact, high-power e-axle systems and premium drivetrains for performance EVs, often via co-development deals with OEMs that have niche or luxury positioning.
Recent, illustrative corporate developments tracked in the study — from modular-drive unveilings to high-voltage drivetrain partnerships and mass-produced 7-in-1 e-axle introductions — concretize how capability investments are translating into competitive momentum and commercial footprints.
Supply-chain and raw-material imperatives
Material and semiconductor realities are among the most immediate constraints on growth. Processing of certain rare-earth elements used in traction magnets is heavily concentrated, creating sourcing vulnerability that directly impacts motor architecture choices. Meanwhile, lithium prices have experienced dramatic declines from 2023 peaks even as cobalt and nickel remain volatile and copper demand intensifies with electrification. Silicon carbide promises step changes in inverter efficiency but brings new supply and cost risks. The report offers concrete mitigation pathways — design alternatives (e.g., magnet-free motors), strategic procurement, and joint-investment models — that can materially reduce execution risk.
Regulatory realism — from CO2 targets to particulate limits
Regulatory developments, particularly in Europe, are elevating requirements beyond tailpipe CO2 to include battery durability and non-exhaust emission considerations (brake and tyre particulates). These changes increase validation scope for drivetrain systems and push cost into both R&D and testing budgets. Companies that align engineering roadmaps with regulatory trajectories early will secure faster access to regulated markets and minimize retrofit liabilities.
Three strategic pathways for 2026
- Scale and platform leadership. Prioritize modular 400V/800V architectures, invest in manufacturing scale for motors and inverters, and secure long-term supply agreements for key components to win volume-driven cost curves.
- Performance differentiation and technology ownership. Focus on high-efficiency architectures (SiC, integrated 7-in-1 solutions, multi-speed e-transmissions) and partner with premium OEMs to establish differentiated, higher-margin powertrain solutions.
- Risk-managed diversification and services. Build aftermarket, software-enabled optimization services, and diversified sourcing strategies (including localized production and strategic inventories) to buffer commodity and geopolitical shocks.
How boards and strategy teams should use the study
- Inform capital allocation deliberations: Use the report’s scenario outputs to size 2026–2028 capex ranges under divergent commodity and regulatory pathways.
- Drive supplier selection and contracting: Apply our supplier scores and risk maps to structure multi-year supply agreements, performance-based milestones, and joint-investment clauses.
- Prioritize product roadmaps and validation plans: Map feature launches against regulatory milestones and certification cycles to reduce time-to-market and warranty exposure.
- Screen M&A targets and partnerships: Use the M&A heatmap and capability overlay to accelerate inorganic growth where internal build is sub-scale or time-prohibitive.
PW Consulting’s Worldwide Automotive Electric Drivetrain Components Market report blends macro market sizing, detailed technology assessment, competitive benchmarking, and supply-chain risk analysis into a single, actionable package for 2026 decision-making. The executive brief above highlights our key strategic takeaways while preserving the proprietary segmentation, supplier scorecards, and granular financial forecasts that form the report’s commercial value. For organizations setting strategy in 2026, that granular intelligence — including downloadable datasets, interactive dashboards, and supplier negotiation templates — is decisive.
For access to the full report, interactive dashboards, and bespoke briefing options for your executive team, please visit the PW Consulting market reports page or contact our industry practice to schedule a private walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Electric Drivetrain Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Biliary Catheters Market Poised for 5.48% CAGR, Reaching USD 937.75 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Biliary Catheters Market — Strategic Outlook for 2026
PW Consulting’s latest Worldwide Biliary Catheters Market study delivers a decision-grade perspective for life sciences executives, strategy teams, and investors preparing for 2026. Grounded in a rigorous 2020–2025 historical base and a 2026–2032 forecast horizon, the analysis distills where competitive advantage will be won and lost as the market progresses at a steady mid-single-digit compound annual growth rate.
Worldwide IT Spending in Public Sector Market
Why this report matters for 2026 planning
The biliary catheters market is maturing. After recovering through 2020–2025, the industry enters 2026 with momentum—the market size expands from a mid‑hundreds million USD base in 2025 and is forecast to continue upward through the 2026–2032 horizon at a projected CAGR of approximately 5.48%. By 2032 the market is expected to be meaningfully larger than it is today, creating a window for strategic moves that will deliver outsized returns to the companies that align product, regulatory and commercial execution with evolving clinical practice.
Rail Transit Permanent Magnet Synchronous Motor Market
For 2026 decision-makers, the critical question is not whether the market grows, but where growth and margin expansion will concentrate. This report provides the directional conviction teams need—rooted in proprietary modeling, scenario testing and competitive diagnostics—while deliberately withholding granular segment-level tables in this briefing to protect the report’s full strategic IP and to incentivize direct engagement with our analysts for custom insights.
Worldwide Spraybooths Market
Macro trajectory and what it implies
- Predictable growth, favorable structural tailwinds: The market demonstrates consistent growth through our historical window and into the forecast period, signaling sustained demand driven by aging populations, rising incidence of biliary disorders, greater adoption of image-guided percutaneous interventions, and shifting care setting dynamics.
- Concentration and competition: The market exhibits moderate concentration—the top three players account for a substantive portion of revenue, and the top five further increase that share—creating an environment where scale matters for distribution, contracting and kit-based procurement.
- Product evolution as a margin lever: Features such as locking loops, radiopaque markers, hydrophilic coatings, larger drainage apertures and reinforcement (e.g., nitinol) are observable differentiators. Device makers that convert these features into clear clinician value (shorter procedure time, reduced complications, simpler inventory) will command premium pricing and uptake.
Practical, actionable deliverables in the full report
PW Consulting’s deliverables are tailored for teams that must act in 2026. The full report includes:
- Robust top‑down and bottom‑up market models with annualized forecasts through 2032 and scenario sensitivities for reimbursement, regulation and clinical adoption.
- Go‑to‑market playbooks segmented by product strategy (including external, internal and conversion catheter approaches), channel design, and hospital vs. ambulatory deployment tactics.
- Competitive benchmarking across product attributes, channel strength, regulatory footprint and commercial partnerships, plus an acquisition target short‑list and synergy estimates.
- Regulatory and reimbursement mapping that aligns device features to CPT pathways and FDA device classifications—enabling faster commercialization timelines and reduced regulatory friction.
- A set of prioritized 12‑ and 24‑month initiatives for commercialization, clinical evidence generation and supply chain resiliency that can be operationalized immediately.
Competitive landscape — strategic takeaways
The market features global medtech leaders alongside regional specialists. Players that combine differentiated device design with broad clinician access and dependable regulatory pathways are best positioned to grow share in 2026. Key competitive themes we surface in the report include:
- Feature-driven differentiation: Boston Scientific and Merit Medical have invested in design features—locking loop options, radiopaque markers, hydrophilic coatings and increased drainage area—that map directly to clinician workflow and patient outcomes. These features are often the primary basis for premium contracting in high-volume centers.
- Technique and kit optimization: Cook Medical and Argon Medical have emphasized multipurpose designs and Seldinger-compatible product families that reduce procedural variability. Offering procedure-ready kits with curated consumables remains a high-impact commercial strategy.
- Performance claims backed by engineering: BD’s use of reinforcement technologies to minimize kinking and ConMed/AngioDynamics’ broad interventional portfolios create bundling opportunities across drainage and access products that health systems value.
- Regional specialists and cost‑effective alternatives: Smaller manufacturers—such as Bioteque, Devon Innovations and Manish Medi Innovation—compete on price, procedural availability and local regulatory familiarity. Their presence ensures tiered procurement strategies remain relevant across markets.
While this briefing highlights company strengths, the full report maps each competitor against a matrix of product attributes, clinical evidence, distribution reach and recent regulatory events—giving executives the evidence base required to prioritize partnerships, licensing or M&A discussions in 2026.
Regulatory and reimbursement dynamics to prioritize
- FDA classification and pathways: Most biliary catheter products sit in a Class II regulatory pathway under the FDA (21 CFR 876.5010). This designation streamlines 510(k) strategies but also creates expectations around special controls and post‑market surveillance that must be integrated into product launch planning.
- Recent clearances highlight evolving device complexity: The recent 510(k) clearances for new balloon dilation and biodegradable stent technologies demonstrate the agency’s ongoing engagement with innovations in the biliary space—an important signal for product developers and regulatory teams planning submissions in 2026.
- Reimbursement contours: Procedure coding remains a cornerstone of commercial planning. Established CPT codes for biliary catheter placement and exchanges (including codes that bundle imaging guidance) inform revenue modeling, hospital charge capture and negotiation strategies with payors.
- Design to cost and documentation: For 2026 launches, manufacturers must design clinical evaluation plans that both support market access and quantify downstream economic benefits (e.g., reduced LOS, fewer reinterventions) to justify premium positioning.
Strategic moves we recommend for 2026
Our testing and engagement with market participants suggest a set of priority actions that should be considered immediately:
- Prioritize differentiated feature sets tied to clinician outcomes: Invest selectively in hydrophilic coatings, enhanced drainage geometry and kink-resistant reinforcements where clinical evidence can be rapidly generated.
- Bundle product and service offerings: Move beyond single SKU sales to procedure kits, integrated disposables and training packages that simplify procurement and create switching costs for hospitals and ASC networks.
- Align regulatory strategy with commercial milestones: Use Class II pathways for speed, but build the post‑market evidence and quality systems necessary to sustain long‑term adoption—especially where new materials (e.g., biodegradable components) are involved.
- Use targeted partnerships for geographic acceleration: For companies lacking direct distribution in key markets, prioritize selective commercial partnerships or licensing to bridge access while maintaining product-level exclusivity on key features.
- Prepare for M&A arbitrage: Given the market’s moderate concentration, larger players will continue to evaluate tuck‑ins that add complementary features, geographic reach or cost‑effective manufacturing. Sellers should prepare diligence packages that highlight recurring procedure volumes and reimbursement alignment.
Decision-grade intelligence, not an encyclopedic dump
The PW Consulting report is intentionally structured as a decision tool. Rather than presenting an exhaustive set of static tables, it combines quantified topline forecasts, scenario analysis and prioritized recommendations designed to be operationalized in 90–180 day sprints. For teams executing commercial launches, regulation, or M&A activity in 2026, this is a playbook that translates market dynamics into clear next steps.
We intentionally withhold segment-level tables and some detailed regional splits from this public summary. Those granular views—covering type, end‑user and regional demand by year—are included in the full report and are available to subscribers and clients seeking tailored growth plans, detailed product‑level modelling, or acquisition diligence support.
How to act now
- Book a briefing with our biliary catheters practice to walk through the model and test your assumptions against our scenarios.
- Obtain the full competitive matrix and clinical evidence roadmap to inform 2026 R&D prioritization and field trials.
- Engage our regulatory desk to align your 510(k) or predicate strategies with reimbursement capture and labeling decisions.
PW Consulting’s Worldwide Biliary Catheters Market report is built for executives who must convert market growth into commercial and clinical advantage in 2026. For direct access to the full dataset, segment breakdowns, and a confidential brief tailored to your portfolio, please visit our report page or contact our healthcare practice leads to schedule a strategy session.
For detailed analysis of this topic, please visit the official page: Worldwide Biliary Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Farrier Products Market Forecast to Grow at a 4.2% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Farrier Products Market: Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market study on Worldwide Farrier Products delivers an evidence‑based, decision‑ready synthesis of the industry entering 2026. Using a 2025 base year and a rigorous historical review (2020–2025) plus a forward projection to 2032, the report quantifies market momentum, interprets structural drivers, and prescribes operational and growth actions that senior executives and investors can deploy immediately. The market has demonstrated steady expansion—growing from an assessed global value in 2020 to a significantly larger base in 2025—and is forecast to continue rising through 2032 at a compound annual growth rate of 4.2%. This briefing highlights the strategic value of the full report for 2026 planning while intentionally leaving granular segment figures behind a gated dataset to preserve the “trailer” experience: enough insight to build confidence, not the full playbook.
Worldwide Artificial Disc Replacement Systems Market
Why this study matters for 2026 strategy
-
Timing: 2026 will be a nexus year in which manufacturers, distributors and service providers must reconcile cost inflation, materials innovation and evolving regulatory expectations while allocating scarce capital. The report converts macro trends into specific choices—pricing, sourcing, product R&D and channel investments—that leaders must decide before year‑end.
Ion Blower Market -
Clarity: PW Consulting synthesizes a multi‑year time series (2020–2025) and a seven‑year forecast (2026–2032) into a concise financial trajectory. That trajectory demonstrates resilient underlying demand and identifies where growth will compound most efficiently for investable returns.
Worldwide Eccentric Screw Pump Market -
Actionability: Beyond market-sizing and historical drivers, the deliverable contains executable modules—cost pass‑through models, SKU rationalization templates, and distribution channel scorecards—that transform insight into boardroom choices.
Market trajectory and macro context
Our aggregated market assessment places the global farrier products market at a materially higher value in 2025 than five years prior and forecasts continued expansion through 2032. The dataset captures the full recovery following supply‑chain volatility and shows a projected rise consistent with a 4.2% CAGR over the forecast horizon. This steady, single‑digit growth profile reflects a mix of mature demand in established equestrian markets and pockets of product and service innovation that incrementally expand market value.
Key macro forces shaping that trajectory include: persistent, stable animal populations that support a baseline level of consumable demand; episodic upstream commodity pressure on steels and alloys; tightening regulatory standards for materials and chemical constituents; and labour market constraints for skilled farrier work. These forces collectively compress margin for lower‑value manufacturers while creating premiumization opportunities for differentiated products and services.
Industry dynamics: cost, compliance, and capability
-
Input cost volatility. Late‑cycle raw material pressures increased production cost bases during the historical window; manufacturers that moved to active hedging, alternative material mixes or closer vertical integration preserved margin and, in some cases, gained share.
-
Regulatory tightening. Recent changes in regulatory frameworks in major markets impose stricter compositional limits on certain alloy constituents. Compliance is non‑negotiable; poor preparation risks product re‑engineering costs and market access delays.
-
Skills scarcity. Skilled farrier labour remains constrained in several key markets. That scarcity elevates the total cost of service and creates demand for tools and systems that reduce on‑hoof time or lower training thresholds.
What the report contains—practical modules for 2026 execution
-
Comprehensive market model: time‑series revenue by year, trend diagnostics, and a scenario engine that lets leadership model upside/downside cases under alternative assumptions for raw material prices, labour availability and regulatory compliance costs.
-
Segment playbooks: go‑to‑market and product strategies for the principal product families and applications, each with recommended price positioning, margin levers, and SKU rationalization frameworks. (Note: detailed segment shares and dollar splits are included in the gated dataset.)
-
Supply‑chain and procurement playbook: supplier risk heatmaps, cost‑to‑serve analyses, and practical recommendations for hedging and near‑shoring to mitigate coil and alloy supply shocks.
-
Regulatory compliance checklist: a jurisdictional matrix and costed implementation timelines to meet updated material limits and labelling obligations.
-
Commercial acceleration toolkit: channel economics for distributors vs. direct sales, digital conversion tactics for retailers, and partnership frameworks with veterinary and equestrian organizations to drive adoption and upsell.
-
M&A and portfolio strategy: an annotated taxonomy of bolt‑on, consolidation and capability‑acquisition targets aligned to distinct strategic objectives (scale, technical IP, channel access). Our deliverable includes a list of screened targets and valuation heuristics.
Competitive landscape—what leaders are doing
The market remains moderately concentrated at the top, with a handful of legacy and specialized players exerting measurable influence on supply, standards and innovation. These incumbents exhibit differentiated strategies that provide clear playbooks for followers and challengers alike.
-
Mustad Hoofcare (Netherlands) — A global leader with broad manufacturing footprint and an integrated portfolio of tools, horseshoes and consumables. Recent product introductions focused on weight‑optimized metal alloys and traction improvements demonstrate how incumbents use incremental product innovation to defend premium segments and pressure competitors on performance metrics.
-
Kerckhaert Horseshoeing (Netherlands) — Known for premium aluminium and steel horseshoes, the company’s strategy emphasizes product refinement and trade‑show presence to sustain a high‑value, brand‑led position. Their cadence of product refreshes reinforces the importance of continuous R&D to maintain relevance among professional farriers.
-
St. Croix Forge (USA) — A U.S. manufacturer rooted in forged steel traditions, their product catalogue refreshes and new toe‑clip lines reflect a dual strategy: protect core forged steel demand while selectively adopting design variants to capture adjacent needs.
-
Anvil Brand, Diamond Horseshoe Supply and Pedigree Forge (USA) — These firms focus on tooling breadth and channel intimacy in North America. Their performance underscores the competitive advantage of distribution networks and relationship capital in professional end markets.
-
Forg‑In (Belgium) and Euroforge (UK) — Suppliers emphasizing specialized anvils, stands and artisan‑grade shoes illustrate the fragmentation opportunity at higher price points and bespoke manufacturing. Small, high‑skill producers can command outsized margins when paired with targeted export strategies.
Collectively, the top firms sustain market influence but do not form an impenetrable oligopoly. PW Consulting’s concentration analysis shows a market where leading players matter, yet meaningful room remains for focused challengers, product innovators and vertically integrated entrants.
Recent market signals and what they mean for 2026
-
Product innovation momentum. High‑profile launches and catalogue updates from established manufacturers signal a continuing shift toward lighter, more performance‑oriented horseshoes and complementary tooling. Firms that invest in materials science and ergonomics will capture premium placements in professional channels.
-
Channel and catalogue refreshes. Regular catalog and portfolio updates among mid‑market suppliers point to an active product renewal cycle—an opportunity for competitors to accelerate SKU rationalization and targeted marketing to capitalize on channel attention.
-
Input volatility and labour pressures. Recent commodity and labour trends have raised the cost of goods sold and service delivery. Companies that deploy disciplined cost pass‑through frameworks and invest in productivity‑enhancing tools will protect margins better than peers who rely on volume alone.
-
Regulatory tightening. Stricter material restrictions in key jurisdictions require proactive compliance programs. Early movers who redesign alloys and secure compliant supply chains will avoid disruptive rework and potentially monetize compliance as a product benefit.
Five imperatives for executive teams in 2026
-
Re‑price and segment profit pools. Adopt dynamic pricing models that reflect material cost volatility and differentiate pricing by channel, product performance and service level. Use our pricing scenario tool to test customer elasticity and margin outcomes.
-
Invest in materials and product differentiation. Prioritize R&D in alternative alloys and hybrid designs to address both cost pressures and demand for lighter, longer‑lasting shoes. Consider partnerships with metallurgy specialists to accelerate time‑to‑market.
-
Operationally de‑risk the supply chain. Implement supplier diversification, strategic inventory cushions for critical inputs, and selective near‑shoring for fast‑moving SKUs to reduce lead times and protect service levels.
-
Monetize professional services. Create training, certification and subscription‑based offerings for farriers that lock customers into premium consumables and tooling ecosystems while addressing the skilled‑labour shortage.
-
Pursue targeted M&A and capability buys. Use M&A to acquire niche IP, specialty manufacturing or distribution footprints that accelerate entry into adjacent markets and consolidate fragmented regional supply.
Next steps: how PW Consulting helps
PW Consulting’s full report contains the complete set of year‑by‑year market values, the segmentation matrices, an interactive financial model, and a suite of executable templates designed for boardroom adoption. For executives building 2026 budgets, the report provides the empirical foundation to stress‑test assumptions, quantify margin impact under different cost scenarios, and prioritize investments with the highest risk‑adjusted returns. To preserve strategic value, detailed segment splits and company‑level financial proxies are provided only through our subscription portal and bespoke advisory engagements.
For an executive briefing, model walkthrough, or to license the complete dataset and benchmarking tools, contact PW Consulting. The full report equips leadership teams with the clarity and operational playbooks necessary to convert the market’s steady growth into measurable competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Farrier Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ceramic Flap Disc Market to Expand at a 6.15% CAGR, New Report Reveals
By pmarketresearch, 2026-08-18
Worldwide Ceramic Flap Disc Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Ceramic Flap Disc Market (base year 2025, forecast 2026–2032) is designed as an executive-grade decision tool for manufacturing leaders, procurement heads, private equity investors, and product strategy teams planning for 2026. The market is entering a sustained growth phase — from an assessed market size of USD 760.5 Million in 2025 to a projected USD 1,154.9 Million by 2032, representing a compound annual growth rate (CAGR) of 6.15% over the forecast window. This briefing highlights the report’s strategic value without disclosing the granular segmentation essential to competitive advantage — a deliberate “trailer” approach to prompt direct access to the full dossier for transaction-critical data.
Worldwide Multiparameter Meters Market
Why this market matters in 2026
- Durable demand drivers: Metal fabrication, welding finishing, and transport manufacturing remain core consumption points for ceramic flap discs, underpinned by industrial refurbishment cycles and ongoing emphasis on productivity in fabrication shops.
- Margin and productivity levers: Ceramic technology continues to displace traditional abrasives in high-stock removal and long-life grinding use cases, offering productivity gains that materially change TCO calculations at scale.
- Consolidation opportunity: Market concentration is moderate — the top three suppliers account for roughly a third of sales (CR3 ~35.5%) and the top five about half (CR5 ~48.2%) — creating openings for scale players and focused challengers to expand via product differentiation and channel optimization.
What the numbers tell strategic teams
The market trajectory we model reflects a steady recovery and structural expansion across 2026–2032. The 6.15% CAGR implies that firms who secure sourcing, qualification, and product-placement wins in the next 12–18 months will capture disproportionate upside as the category grows. For investors evaluating roll-up strategies or product-line investments, the growth profile balances predictable industrial demand with pockets of innovation (grain technologies, bonding systems, and wheel geometries) that can produce margin expansion.
Worldwide White Cool Roof Coating Market
Core dynamics shaping the landscape
- Raw material and cost pressure: Calcined alumina — a primary feedstock for ceramic grains — showed upward pricing pressure in 2024, with average prices rising due to energy cost pass-throughs. Material cost volatility translates directly into margin sensitivity for mid-tier producers and creates opportunities for vertically integrated players or those with hedging strategies (USGS, 2025).
- Safety and regulatory alignment: ANSI B7.1-2022 limits and the recent EN 13743:2023 specification for fixed machinery use have sharpened OEM and industrial buyer scrutiny on rated speeds and product traceability. Compliance capability is now a procurement table-stake and a differentiator in public-sector and heavy-industrial contracts.
- Trade and supply-chain distortion: Global abrasive flows remain concentrated; major exporting countries continue to supply high volumes into global markets while facing tariff and anti-dumping actions in key destinations. Recent trade measures affecting exports to the EU underscore the need for diversified sourcing strategies and local inventory positioning.
- Labor and productivity context: Tight labour markets in advanced economies are increasing the value of consumables that lower cycle times and rework rates. Buyers are explicitly benchmarking abrasive life-per-job and operator throughput when selecting flap discs.
Competitive landscape – what to watch
The market features a mix of multinational incumbents with broad abrasive portfolios and regional specialists focused on narrow application sets. Leading names include:
Worldwide Grocery Delivery Software Market
- 3M (St. Paul, Minnesota) — Leveraging precision-shaped grain technology to position Cubitron II and related ceramic products as productivity enablers in metalworking and welding.
- Saint-Gobain Abrasives (Norton) (Worcester, Massachusetts) — Emphasizes systemic product families optimized for stainless and carbon steel and continues to iterate product formulations showcased at major industry events.
- Klingspor (Haiger, Germany), Tyrolit (Schwaz, Austria), PFERD (Marienheide, Germany) — Strong regional manufacturing footprints with tailored offerings for heavy grinding, pipeline welding, and seam removal.
- Hermes Schleifmittel, VSM Abrasives, Weiler Abrasives, United Abrasives, Sia Abrasives — A cohort of specialists delivering differentiated grain recipes, open-coat constructions, and application-focused engineering support for sectors such as shipbuilding and aerospace.
Recent proprietary observations confirm ongoing product activity: new launches targeted at pipeline welding and weld-finishing applications, and trade-show rollouts that indicate continued R&D investment (e.g., product launches and exhibits in 2023–2024). For buyers and OEMs, supplier roadmaps increasingly matter as much as current catalog performance.
What the full report contains (practical, transaction-ready assets)
PW Consulting’s full market study is structured to support immediate 2026 decision-making across commercial, procurement, and investment teams. Key deliverables include:
- Top-line market sizing and a 2020–2032 time series with scenario paths (Base, Upside, Downside) that model demand elasticity against raw material and labour-cost shocks.
- Supply-side scorecards: manufacturing profiles, capacity maps, lead-times, and quality certifications for primary manufacturers and key private-label suppliers.
- Procurement playbook: sourcing levers, bundled-commodity negotiation tactics, inventory optimization models, and a supplier RFP template calibrated for performance and compliance metrics.
- Product benchmarking and testing protocols: lab-to-shop floor validation checklists, life-cycle abrasion metrics, and safety compliance matrices aligned to ANSI and EN standards.
- Scenario-based financial models: sensitivity analyses showing margin impact under varying calcined alumina cost curves, tariff scenarios, and volume discounts.
- M&A and partnership intelligence: buyer-seller maps, integration risks, and five prioritized inorganic growth theses with acquisition candidate archetypes.
- Regulatory and standards tracker: an actionable digest of safety, machine-compatibility, and labeling obligations across major markets to reduce bid risk in regulated tenders.
To preserve competitive value, the full report contains the detailed regional and application-level splits, price-by-variant matrices, and per-supplier revenue stacks. These are intentionally omitted here to maintain the “trailer” positioning of this release; access to those granular tables is available on our report landing page.
Strategic moves we recommend for 2026
- Prioritize supplier audits and dual-sourcing pilots now. With trade measures and material-price volatility present, locking in qualified second-source capacity and negotiated hedges will protect margins and service levels.
- Invest in product qualification tied to operator productivity KPIs rather than list-price alone. Procurement should require suppliers to demonstrate job-level throughput, wheel life, and rework-reduction evidence as part of commercial terms.
- Pursue modular MRO contracts with performance SLAs that convert abrasive performance into quantifiable savings — days-to-complete and first-pass yield metrics are persuasive with plant leadership.
- For manufacturers and PE investors: consider bolt-on acquisitions that expand application breadth (e.g., welding-focused product lines) or geographic logistics capabilities to mitigate tariff and lead-time exposure.
- Embed compliance as a commercial filter: demand ANSI and EN conformity statements up-front and treat non-compliant offers as high-risk even if price-competitive.
Near-term watchlist (next 12 months)
- Raw-material cost trajectory for calcined alumina and its pass-through into list prices.
- Trade policy shifts and anti-dumping outcomes that could reroute abrasive supply chains and create near-term winners and losers.
- New product introductions and validated field trials from major OEMs that can reset buyer expectations for disk life and cut-rates.
- Labour-market impacts on adoption: as skilled welder shortages persist, productivity-enhancing consumables will continue to command a premium.
Conclusion — how PW Consulting’s report accelerates 2026 outcomes
For decision-makers preparing budgets, sourcing strategies, or investment theses for 2026, this market’s steady growth and the dynamics outlined above create both predictable revenue backdrops and tactical uncertainty. Our study translates the macro trajectory — USD 760.5 Million in 2025 expanding at a 6.15% CAGR — into operational playbooks: how to hedge cost exposure, how to prioritize supplier engagements, and where to place high-return product investments. The dossier is engineered to convert market intelligence into executable steps that protect margins and accelerate adoption of higher-value ceramic technologies.
For immediate access to the full data tables, granular regional and application splits, supplier-level revenue estimates, and the complete procurement toolkit, please visit PW Consulting’s report page. The full report provides the granular insight necessary to finalize supplier contracts, capital allocations, and M&A screening in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Flap Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com